Leasing vs. Buying a Car: What's Better in 2025?
Crunch the numbers, weigh your lifestyle, and ride smart
4 min. read
For many people, when it’s time to get a new set of wheels, one big question may come to mind: should you lease or buy? Both options have advantages and drawbacks. But the “right” choice for you isn’t a one-size-fits-all. The answer depends on your budget, driving habits, and long-term financial goals.
At WorkMoney, we’re here to break it down so you can make a decision that works for you and your wallet. We’re not selling cars. We’re here to help you cut your total costs, take advantage of money-saving programs, and drive away feeling confident about your choice.
Car Leasing vs. Buying — The Basics
Deciding whether to lease or buy a car is often the second biggest money choice you’ll make after housing. And it’s not just about getting from point A to point B. Your decision can shape your budget for years. Here’s how each option works.
How Leasing Works
Leasing is a long term rental agreement that lasts typically for 2–4 years. The payments are often lower than getting a loan for the same vehicle. But you'll return the car when your lease is up. You can then choose to lease again, buy the car, or walk away.
Here's a look at the pros and cons.
Pros:
Lower monthly payments
New car every few years
Warranty coverage limits repair costs
Cons:
Mileage limits (around 10,000–15,000/year)
Wear-and-tear fees
No ownership at lease end
How Buying Works
Buying a car, whether you pay cash or finance, means you can own the vehicle outright. You can also keep it for as long as you want, customize it, and sell it when you’re ready.
Let's look at the pros and cons.
Pros:
Build equity
No mileage limits
No payments once paid off
Cons:
Higher monthly cost
Pay for repairs after warranty
Depreciates over time
If you like driving a newer car every few years, leasing can be appealing. But if you rack up a lot of miles or want to be payment-free someday, buying might be better.
Next, let’s break down the real numbers so you can see how each choice could impact your monthly budget.
Comparing Total Monthly Costs
On paper, leasing almost always looks cheaper month-to-month. But monthly payments aren’t the whole story. To do a realistic comparison, you need to include:
Insurance (leased cars often require higher coverage limits)
Routine maintenance and repairs (like oil changes, tires)
Mileage overage charges for leases
Below are examples based on two different household incomes:
These examples don’t include other ways to save in your budget, but we’ll cover those later.
Total Long-Term Cost
Cars lose value as they age — this is called depreciation. A new car can lose 20% of its value in the first year and around 60% after five years.
With a lease: The car’s remaining value (residual value) at the end of your lease goes back to the dealer when you turn it in. You don’t get that money.
With buying: You own the car and can sell it later. While it will still lose value, you keep whatever it’s worth when you sell or trade it in.
Pro Tip: Driving fewer miles and keeping the car in good condition can help you sell for more money if you own it, or avoid extra fees if you lease.
Total Monthly Cost Calculator — Lease vs. Buy
Here’s a quick calculator to compare leasing vs. buying, and it shows how savings programs like Arbor and Insurify can make buying a car more affordable.
In this example, WorkMoney partner savings programs can help cut the monthly gap between buying and leasing from $150 to $105, which makes buying a lot more competitive.
Household income
Lease
Buy
$49,999 and under
$280 monthly payment
+ $90 insurance
+ $25 maintenance
= $395 total
$400 monthly payment
+ $75 insurance
+ $40 maintenance/repairs
= $515 total
$50,000 to $150,000
$350 monthly payment
+ $95 insurance
+ $30 maintenance
= $475 total
$500 monthly payment
+ $80 insurance
+ $50 maintenance/repairs
= $630 total
Expense Category
Leasing
Buying
Base monthly payment
$320
$480
Insurance
$140
$120
Maintenance & repairs
$40
$110
Subtotal monthly cost
$500
$770 ($270 more)
Arbor utility savings applied
-
-$25
Insurify insurance savings applied
-
-$20
Monthly cost
$500
$725
Lifestyle Factors That Affect Your Decision
Cost isn’t the only thing to think about — your lifestyle and future plans can make one option a better fit. Here are two key things to consider.
Driving Habits
If you drive a lot—say over 15,000 miles a year—buying might make more sense. Most leases cap mileage around 15,000 per year, and going over can trigger costly excess-mileage fees. If you drive less, leasing can work in your favor.
Life Changes
If you’re planning any big life shifts, it could help you decide. A new job with a longer commute, a new baby, or a move to a city with great public transit could all affect whether leasing or buying makes more sense.
Call out: “For anyone looking to be frugal, buying a used but fairly recent mid-tier car and driving it for years is the right choice.” — Reddit user
Hidden Costs and Surprises
Your monthly payment for your new car is only one of several costs with your transportation. Here are some expenses that many people may not initially consider. However, they can throw off your entire budget if you’re not ready. These can include:
Lease-end fees: Extra charges for wear and tear can add up.
Early termination penalties: Ending a lease early is expensive.
Out-of-warranty repairs: When you buy, you’re responsible for repair bills once the warranty expires.
While these aren’t part of your regular monthly costs, they are important to plan for to avoid being blindsided.
Government & Partner Savings Opportunities
Before making the final decision whether to lease or buy, know that the following programs may help lower your overall costs:
Government incentives: If you’re eyeing an electric vehicle (EV), you may qualify for a federal EV tax credit worth thousands. Buyers get this back at tax time. Leasing companies sometimes pass it along as lower payments — but not always, so it pays to ask.
WorkMoney partner savings:
Example: When you combine the financial incentives from Arbor and Insurify, you could potentially save hundreds of dollars.
At WorkMoney, we always remind readers that these programs aren’t handouts. They’re tools to help you keep more of your money.
Final thoughts
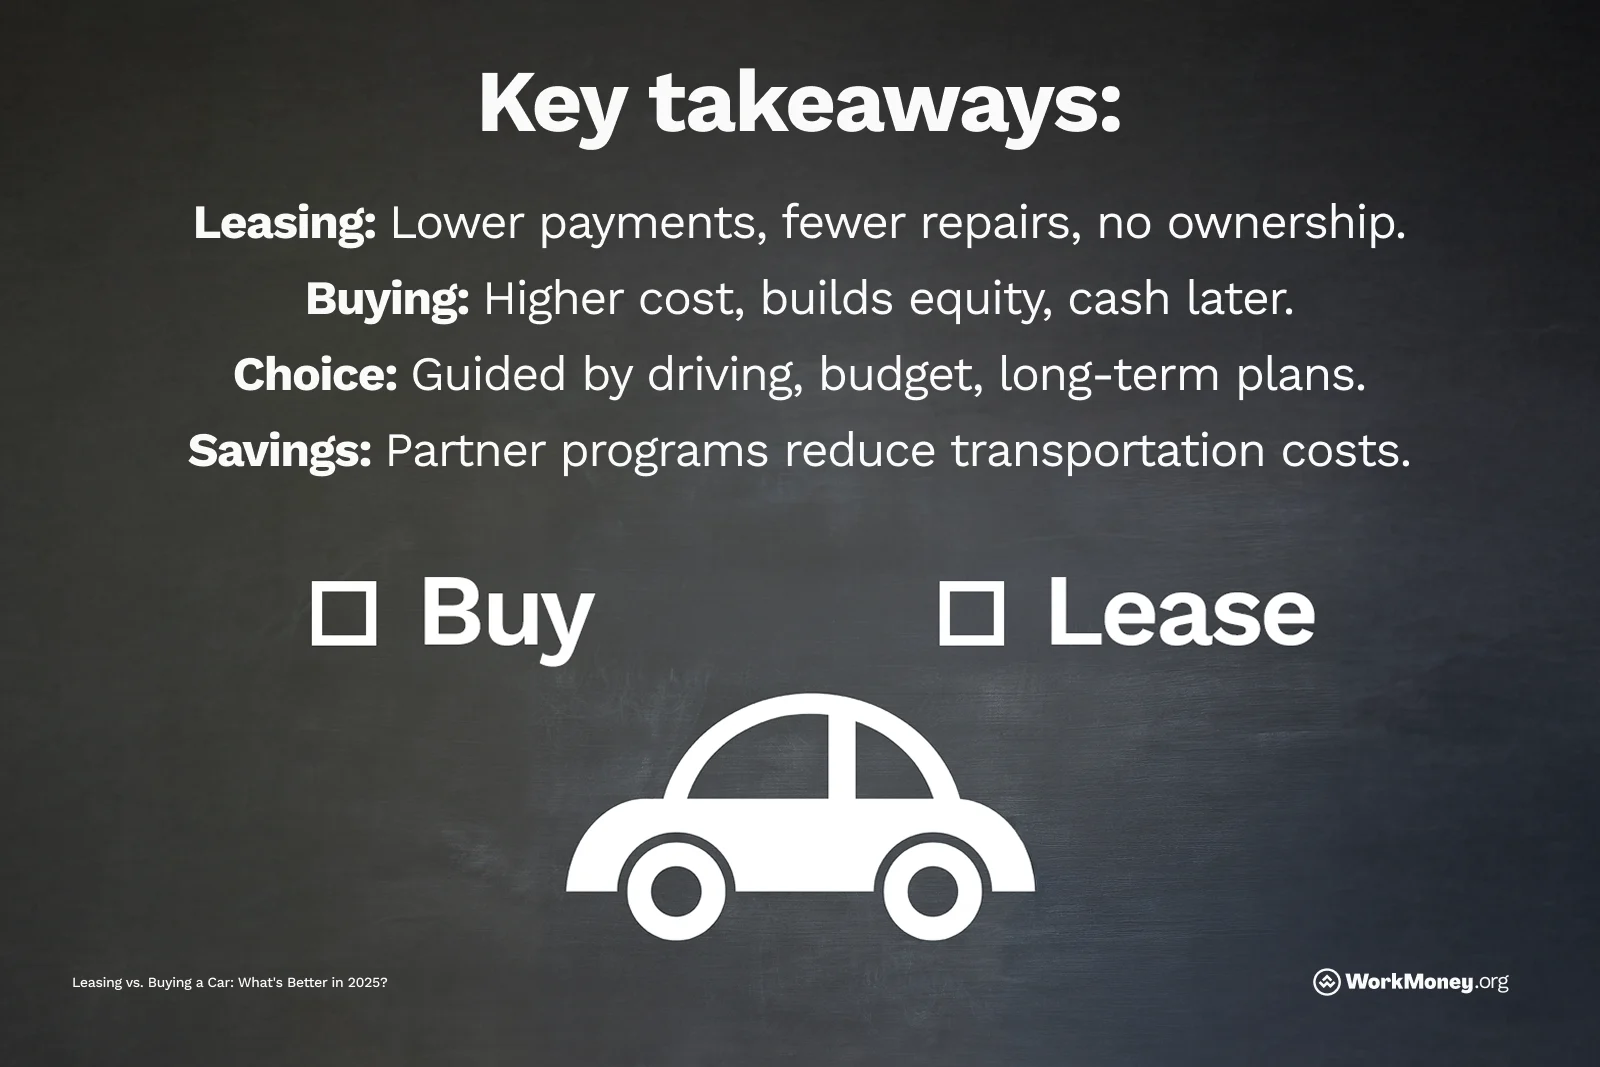
There is no one-size-fits-all answer to the question of whether you should lease a car or buy. It comes down to your lifestyle and budget. Leasing often means lower payments and the chance to drive a new car every few years, but you’ll never be free of monthly bills. Buying costs more upfront, but once the car is paid off, you could free up hundreds each month. The best choice is the one that keeps your finances steady and works for your long-term goals.
Take the next step
Slash your car insurance premiums
Save up to $1,100 a year on your vehicle with Insurify
Easily lower your car loan payments
See if you can save over $1,900 a year by refinancing your auto loan through Caribou.
Was this information helpful?
About the Author
DeShena Woodard
DeShena Woodard is a Financial Freedom Coach, Certified Life Coach, freelance personal finance writer, and podcast host. Her story, advice, and expertise have been featured in prominent outlets such as CNN Underscored, Business Insider, Yahoo Finance, NerdWallet, and more. Through her platform, Extravagantly Broke, she helps women take control of their finances with simple, stress-free strategies—without sacrificing the joy of everyday life. When she’s not writing or coaching, DeShena enjoys traveling, biking, and spending time with her family.